Mushak 6.6 বা মূসক ৬.৬ হলো উৎসে কর কর্তন সনদপত্র (VDS certificate)। কোনো ব্যাংক, কোম্পানি, এনজিও বা সরকারি অফিস সরবরাহকারীর বিল থেকে ভ্যাট কেটে রাখলে সেই কাটা টাকার প্রমাণ হিসেবে এই সনদ দিতে হয়। সনদ না পেলে সরবরাহকারী তাঁর রিটার্নে হ্রাসকারী সমন্বয় নিতে পারেন না—ফলে একই ভ্যাট দুবার দেওয়ার ঝুঁকি তৈরি হয়। কে সনদ দেবেন, কত দিনের মধ্যে, কোন তথ্য লাগবে, আর সরবরাহকারী কীভাবে সমন্বয় নেবেন—সহজ ভাষায় পুরো গাইড।
১. Mushak 6.6 কী: উৎসে কর কর্তন সনদপত্রের সহজ ব্যাখ্যা
মূল্য সংযোজন কর ও সম্পূরক শুল্ক আইন, ২০১২-এর ধারা ৪৯ অনুযায়ী নির্দিষ্ট কিছু প্রতিষ্ঠান সরবরাহকারীকে বিল পরিশোধের সময় নির্ধারিত হারে ভ্যাট কেটে সরকারি কোষাগারে জমা দেয়। এটাই উৎসে মূসক কর্তন, ইংরেজিতে VAT Deducted at Source বা VDS। আর ধারা ৫৩ বলছে, উৎসে কর কর্তনকারী সত্তা নিবন্ধিত সরবরাহকারীর কাছ থেকে সরবরাহ নিলে মূল্য পরিশোধের সময় বোর্ড নির্ধারিত পদ্ধতিতে উৎসে কর কর্তন সনদপত্র ইস্যু করবে। এই সনদপত্রের নির্ধারিত ফরমই হলো মূসক-৬.৬।
সহজ করে বললে: সরবরাহকারী তাঁর বিক্রয়ের পুরো ভ্যাট নিজের রিটার্নে উৎপাদ কর হিসেবে দেখান। কিন্তু সেই ভ্যাটের একটি অংশ ক্রেতা আগেই কেটে সরকারকে দিয়ে দিয়েছে। মূসক ৬.৬ সেই কাটা অংশের দালিলিক প্রমাণ। এই প্রমাণ দেখিয়েই সরবরাহকারী নিজের রিটার্নে হ্রাসকারী সমন্বয় নেন, যাতে একই ভ্যাট দুবার পরিশোধ করতে না হয়।
- ক্রেতা (VDS সত্তা) এর জন্য: ভ্যাট কেটে জমা দেওয়ার দায় পূরণের প্রমাণ।
- সরবরাহকারীর জন্য: রিটার্নে হ্রাসকারী সমন্বয় দাবির একমাত্র শক্ত ভিত্তি।
- কর কর্তৃপক্ষের জন্য: ক্রেতার বৃদ্ধিকারী সমন্বয় আর সরবরাহকারীর হ্রাসকারী সমন্বয় মিলিয়ে দেখার সূত্র।
২. কে উৎসে মূসক কাটবেন: VDS সত্তার তালিকা
আইনের সংজ্ঞা ও উৎসে মূসক কর্তন বিধিমালা অনুযায়ী সাধারণত নিচের প্রতিষ্ঠানগুলো উৎসে কর কর্তনকারী সত্তা হিসেবে গণ্য হয়:
সরকারি খাত
- মন্ত্রণালয়, বিভাগ ও অধিদপ্তর
- আধাসরকারি ও স্বায়ত্তশাসিত প্রতিষ্ঠান
- রাষ্ট্রায়ত্ত প্রতিষ্ঠান ও স্থানীয় কর্তৃপক্ষ
আর্থিক খাত
- ব্যাংক
- বীমা কোম্পানি
- অন্যান্য আর্থিক প্রতিষ্ঠান
অন্যান্য
- লিমিটেড কোম্পানি
- এনজিও ব্যুরো বা সমাজসেবা অধিদপ্তর অনুমোদিত প্রতিষ্ঠান
- মাধ্যমিক ও উচ্চমাধ্যমিক পর্যায়ের শিক্ষা প্রতিষ্ঠান
অর্থাৎ আপনার প্রতিষ্ঠান যদি একটি প্রাইভেট লিমিটেড কোম্পানি হয়, তাহলে ভাড়া, ঠিকাদারি, পরামর্শ, নিরাপত্তা, পরিবহনসহ অনেক সেবার বিল পরিশোধের সময় আপনাকেই উৎসে মূসক কাটতে হতে পারে—এবং প্রতিবার Mushak 6.6 ইস্যু করতে হবে। কোন সেবায় কত হারে কাটতে হবে, তা নির্ধারিত হয় বিধিমালার সেবা কোডভিত্তিক তালিকায়; আমাদের TDS ও VDS রেট চার্ট ২০২৬-২৭ দেখুন।
৩. কখন উৎসে মূসক কাটবেন, কোথায় জমা দেবেন
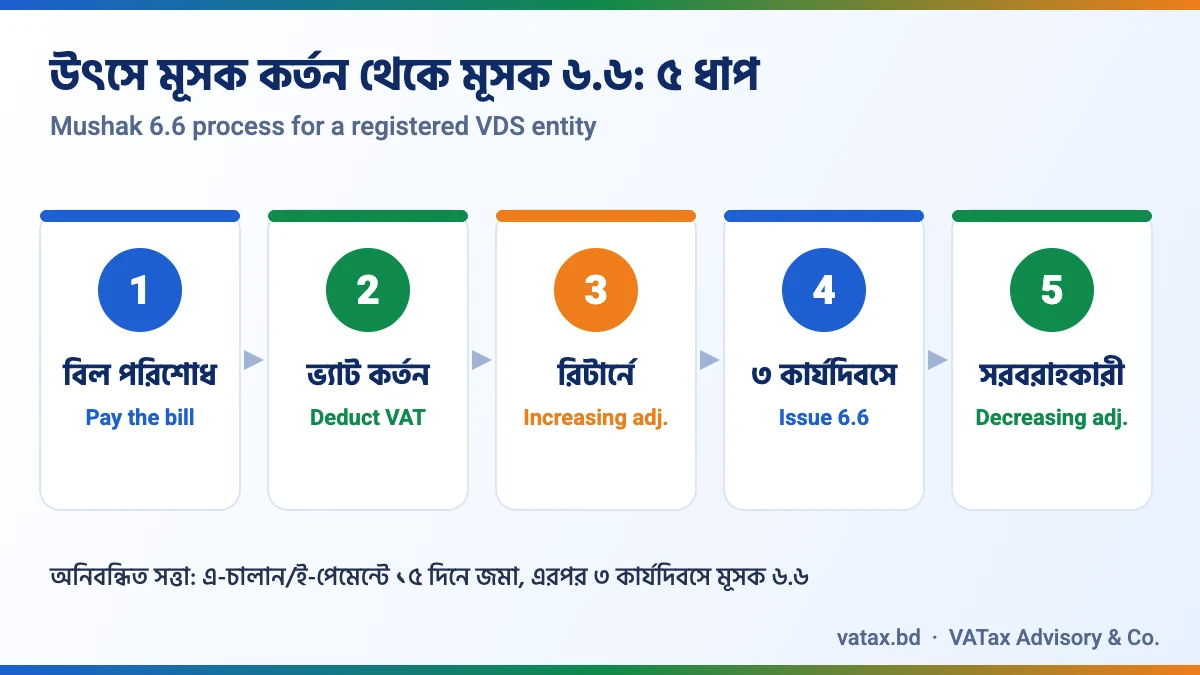
উৎসে মূসক কাটতে হয় বিল পরিশোধের সময়। ২০২৫ সালের ২৭ মে জারি হওয়া এসআরও নং ১৮২-আইন/২০২৫/৩১০-মূসক (উৎসে মূসক কর্তন ও আদায় নির্দেশিকা/বিধিমালা ২০২৫, কার্যকর ১ জুলাই ২০২৫) আগের ২০২১ সালের বিধিমালার জায়গা নিয়েছে। আইসিএবি-তে উপস্থাপিত এক বিশ্লেষণ অনুযায়ী এতে জমা দেওয়ার পদ্ধতি বদলেছে:
| বিষয় | নিবন্ধিত VDS সত্তা | অনিবন্ধিত VDS সত্তা |
|---|---|---|
| কীভাবে জমা | রিটার্নে বৃদ্ধিকারী সমন্বয় হিসেবে দেখিয়ে নিট দায়ের সাথে পরিশোধ | এ-চালান বা ই-পেমেন্টে আলাদাভাবে জমা |
| সময় | সংশ্লিষ্ট কর মেয়াদের রিটার্ন দাখিলের আগে | বিল পরিশোধের ১৫ দিনের মধ্যে |
| মূসক ৬.৬ ইস্যু | রিটার্ন দাখিলের পর ৩ কার্যদিবসের মধ্যে | জমা দেওয়ার পর ৩ কার্যদিবসের মধ্যে |
| প্রমাণ | দাখিলপত্রের তথ্য | চালান/ই-পেমেন্ট স্লিপের নম্বর ও তারিখ |
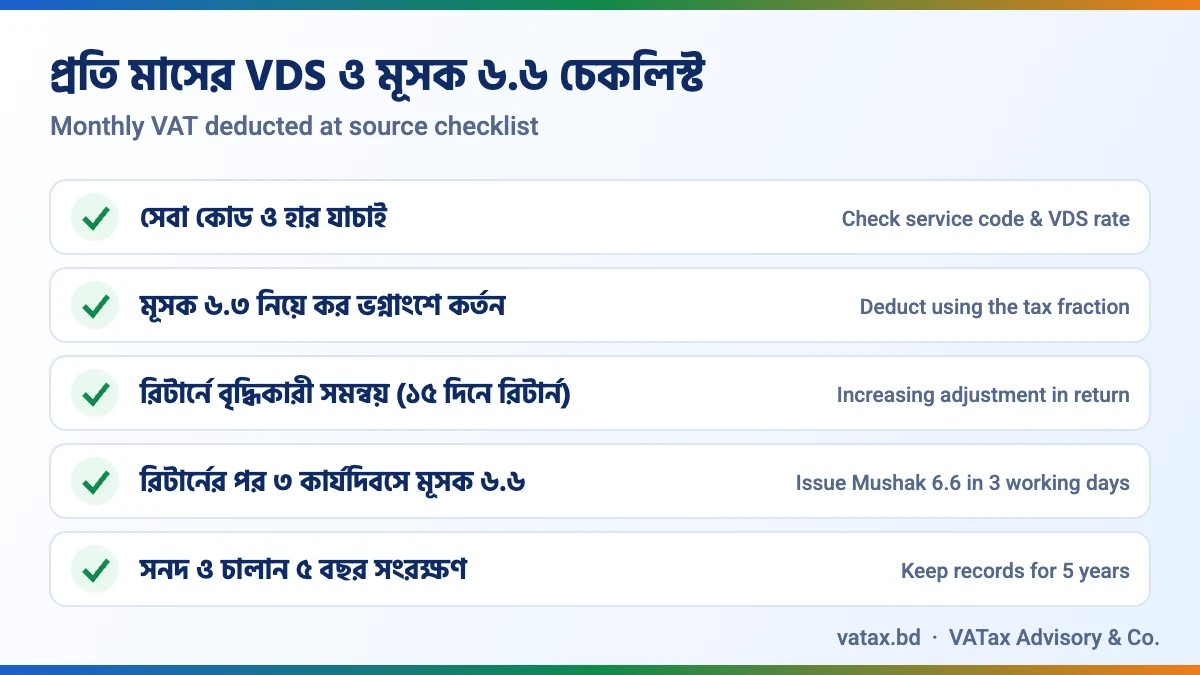
মাসিক রিটার্নের সময়সীমাও মনে রাখুন। মূসক ও সম্পূরক শুল্ক (সংশোধন) অধ্যাদেশ, ২০২৬ অনুযায়ী এখন প্রতি মাসের রিটার্ন কর মেয়াদ শেষ হওয়ার ১৫ দিনের মধ্যে; ব্যাংক, বীমা ও সরকারি-আধাসরকারি-স্বায়ত্তশাসিত প্রতিষ্ঠান পায় ২০ দিন। তাই নভেম্বর ২০২৬-এ পরিশোধ করা বিলের VDS নভেম্বরের রিটার্নে যাবে, আর সেই রিটার্ন দাখিলের পর তিন কার্যদিবসের মধ্যে সরবরাহকারীর হাতে মূসক ৬.৬ পৌঁছাতে হবে। বিস্তারিত পড়ুন: মাসিক ভ্যাট রিটার্ন: ১৫ দিনের নিয়ম।
৪. Mushak 6.6 সনদপত্রে কী কী তথ্য থাকে
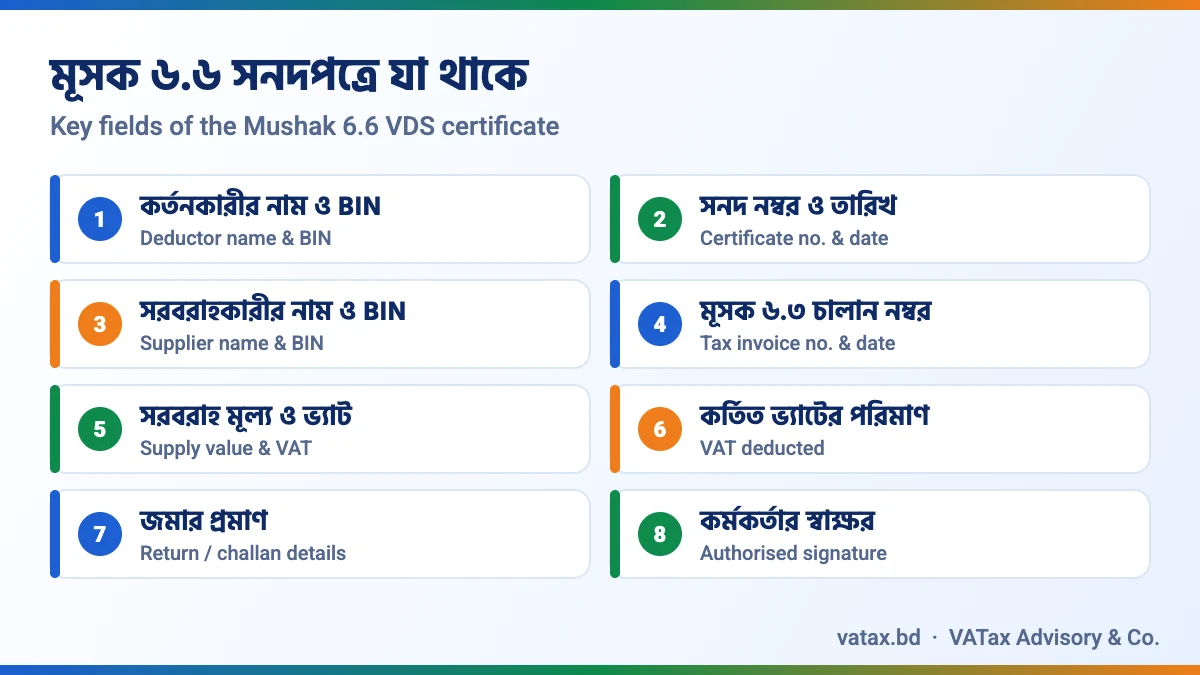
ফরমটি সরল, কিন্তু প্রতিটি ঘর মূল কর চালানপত্রের (মূসক ৬.৩) সাথে হুবহু মিলতে হয়। সাধারণত যে তথ্যগুলো লাগে:
| অংশ | যা লিখবেন |
|---|---|
| কর্তনকারীর তথ্য | উৎসে কর কর্তনকারী সত্তার নাম, ঠিকানা ও BIN (নিবন্ধিত হলে) |
| সনদের তথ্য | সনদপত্রের ক্রমিক নম্বর ও ইস্যুর তারিখ |
| সরবরাহকারীর তথ্য | সরবরাহকারীর নাম, ঠিকানা ও BIN |
| চালানের তথ্য | মূসক ৬.৩ কর চালানপত্রের নম্বর ও তারিখ |
| মূল্য | চালানে দেখানো সরবরাহ মূল্য ও ভ্যাটের পরিমাণ |
| কর্তিত ভ্যাট | প্রকৃতপক্ষে উৎসে কর্তিত মূসকের পরিমাণ |
| জমার প্রমাণ | নিবন্ধিত হলে দাখিলপত্রের তথ্য; অনিবন্ধিত হলে চালান বা ই-পেমেন্টের নম্বর ও তারিখ |
| স্বাক্ষর | দায়িত্বপ্রাপ্ত কর্মকর্তার নাম, পদবি ও স্বাক্ষর |
একটি সনদে একাধিক চালান দেখানো যায়, তবে প্রতিটি চালানের জন্য আলাদা সারি রাখুন। e-VAT সিস্টেম থেকে সনদ তৈরি করলে তথ্য স্বয়ংক্রিয়ভাবে মেলানো সহজ হয়। সনদের একটি কপি সরবরাহকারীকে দিন, একটি নিজের রেকর্ডে রাখুন। আইনের ধারা ১০৭ অনুযায়ী এসব রেকর্ড কমপক্ষে পাঁচ বছর সংরক্ষণ করতে হয়।
৫. উদাহরণ: উৎসে মূসকের হিসাব ও সময়সূচি
ধরা যাক, একটি লিমিটেড কোম্পানি (নিবন্ধিত VDS সত্তা) নভেম্বর ২০২৬-এ একটি নিবন্ধিত সরবরাহকারীকে একটি সেবার বিল পরিশোধ করছে। বিলের ভ্যাটসহ মোট পণ ১,০৭,৫০০ টাকা এবং ধরে নিই ওই সেবায় প্রযোজ্য উৎসে কর্তনের হার ৭.৫%। (সংখ্যাগুলো উদাহরণমাত্র; প্রকৃত হার সেবা কোড অনুযায়ী বিধিমালা থেকে নিন।)
| ধাপ | হিসাব | ফল |
|---|---|---|
| পরিশোধযোগ্য পণ | ভ্যাটসহ বিল | ১,০৭,৫০০ টাকা |
| কর ভগ্নাংশ | ৭.৫ ÷ ১০৭.৫ | — |
| উৎসে কর্তনযোগ্য মূসক | ১,০৭,৫০০ × ৭.৫ ÷ ১০৭.৫ | ৭,৫০০ টাকা |
| সরবরাহকারীকে পরিশোধ | ১,০৭,৫০০ − ৭,৫০০ | ১,০০,০০০ টাকা |
| রিটার্নে দেখানো | নভেম্বরের রিটার্নে বৃদ্ধিকারী সমন্বয় | ৭,৫০০ টাকা |
| মূসক ৬.৬ ইস্যু | রিটার্ন দাখিলের পর ৩ কার্যদিবস | ডিসেম্বরের মাঝামাঝি |
সরবরাহকারী তাঁর নভেম্বরের রিটার্নে পুরো বিক্রয় ও ৭,৫০০ টাকা উৎপাদ কর দেখাবেন। মূসক ৬.৬ হাতে পাওয়ার পর তিনি ৭,৫০০ টাকা হ্রাসকারী সমন্বয় হিসেবে দাবি করবেন। ফলে সরকার একবারই ৭,৫০০ টাকা পায়—ক্রেতার মাধ্যমে।
৬. সরবরাহকারী কীভাবে হ্রাসকারী সমন্বয় নেবেন
- মূসক ৬.৩ দিন: প্রতিটি সরবরাহে নিয়ম মেনে কর চালানপত্র ইস্যু করুন; ভ্যাটের পরিমাণ স্পষ্ট লিখুন।
- পুরো উৎপাদ কর দেখান: রিটার্নের সরবরাহ অংশে পূর্ণ মূল্য ও ভ্যাট দেখান—কাটা অংশ বাদ দিয়ে নয়।
- মূসক ৬.৬ সংগ্রহ করুন: ক্রেতার কাছ থেকে সনদ নিন এবং চালান নম্বর, তারিখ ও অঙ্ক মিলিয়ে দেখুন।
- হ্রাসকারী সমন্বয় নিন: সনদে দেখানো কর্তিত ভ্যাটের সমপরিমাণ হ্রাসকারী সমন্বয় রিটার্নে দাবি করুন।
- সময়সীমা মানুন: ২০২৫ সালের বিধান অনুযায়ী এই সমন্বয় সংশ্লিষ্ট কর মেয়াদ বা পরবর্তী ছয়টি কর মেয়াদের মধ্যে নিতে হয় (আগে ছিল তিনটি)। সময় পেরোলে দাবি হারানোর ঝুঁকি।
বাস্তবে সবচেয়ে বড় সমস্যা হলো ক্রেতা সময়মতো সনদ না দেওয়া। সেজন্য প্রতিটি বড় গ্রাহকের কাছে মাসিক ফলো-আপ তালিকা রাখুন এবং চুক্তিতেই লিখে নিন যে VDS কাটলে নির্ধারিত সময়ের মধ্যে মূসক ৬.৬ দিতে হবে।
৭. কোথায় উৎসে মূসক প্রযোজ্য নয়
- অব্যাহতিপ্রাপ্ত সরবরাহ: আইনের প্রথম তফসিলভুক্ত পণ্য বা সেবা—ধারা ৪৯(১) শুধু অব্যাহতিপ্রাপ্ত নয় এমন সরবরাহে প্রযোজ্য।
- শূন্যহারবিশিষ্ট সরবরাহ: রপ্তানি ও প্রচ্ছন্ন রপ্তানির মতো শূন্যহারের সরবরাহ।
- PKI/POS চালান: ২০২৫ সালের পরিবর্তন অনুযায়ী ক্রেতার নাম ও BIN সংবলিত PKI বা POS যন্ত্রে ইস্যু করা চালানে উৎসে কর্তন হয় না (আইসিএবি-তে উপস্থাপিত বিশ্লেষণ)।
- দেশে উৎপাদিত ওষুধ: ব্যবসায়ীর কাছ থেকে দেশে উৎপাদিত ওষুধ ক্রয়ে কর্তন হয় না (একই সূত্র)।
প্রকল্পের ক্ষেত্রে ধারা ৪৯(৫)-এর সুবিধা—যেখানে মূল সেবা প্রদানকারীর পর্যায়ে ভ্যাট কাটা হয়েছে—এখন কেবল প্রথম স্তরের সাব-কন্ট্রাক্টর বা এজেন্টের ক্ষেত্রে সীমিত বলে আইসিএবি-র বিশ্লেষণে উল্লেখ আছে। নিচের স্তরের সাব-কন্ট্রাক্টরের বিলে VDS প্রযোজ্য হতে পারে।
৮. দায় ও ঝুঁকি
ধারা ৪৯(৪) স্পষ্টভাবে বলছে, উৎসে কর কর্তন এবং কোষাগারে জমার জন্য কর্তনকারী সত্তা ও সরবরাহকারী যৌথ ও পৃথকভাবে দায়ী। এর মানে, ক্রেতা ভ্যাট না কাটলে বা কেটে জমা না দিলে কর কর্মকর্তা দুই পক্ষের যেকোনো একজনের কাছ থেকে তা আদায় করতে পারেন।
- ক্রেতা কেটে রেখেছে কিন্তু রিটার্নে বৃদ্ধিকারী সমন্বয় দেখায়নি—সরবরাহকারীর হ্রাসকারী সমন্বয় অডিটে প্রশ্নবিদ্ধ।
- সনদে চালান নম্বর ভুল—দুই পক্ষের তথ্য মেলে না।
- সময়সীমা পেরিয়ে সমন্বয় দাবি—দাবি বাতিল হয়ে সুদসহ দায় তৈরি হতে পারে।
- অনিবন্ধিত সরবরাহকারীর কাছ থেকে চালান ছাড়া ক্রয়—ভ্যাটের পুরো দায় ক্রেতার।
৯. Mushak 6.6 নিয়ে ৭টি সাধারণ ভুল
- মূসক ৬.৩ না নিয়েই ভ্যাট কেটে সনদ দেওয়া।
- ভ্যাটসহ মূল্যের ওপর সরাসরি হার গুণ করা—কর ভগ্নাংশ ব্যবহার না করা।
- পুরোনো হার ব্যবহার করা; যেমন ২০২৫ থেকে নির্মাণ ঠিকাদারির হার ৭.৫% থেকে ১০% হয়েছে।
- রিটার্ন দাখিলের পর তিন কার্যদিবসের মধ্যে সনদ না দেওয়া।
- সরবরাহকারীর BIN ভুল লেখা।
- সরবরাহকারী পক্ষ থেকে কাটা অংশ বাদ দিয়ে উৎপাদ কর দেখানো—এতে দুইবার সমন্বয় হয়ে যায়।
- সনদ ও চালানের কপি পাঁচ বছর সংরক্ষণ না করা।
১০. ব্যবসায়ীদের এখনই যা করা উচিত
- আপনার প্রতিষ্ঠান VDS সত্তা কি না নিশ্চিত হোন; হলে প্রতিটি সরবরাহকারীর সেবা কোড ও প্রযোজ্য হার তালিকা করুন।
- অক্টোবর ২০২৬-এর রিটার্ন (শেষ দিন ১৫ নভেম্বর) দাখিলের পর তিন কার্যদিবসের মধ্যে সব মূসক ৬.৬ ইস্যু করুন।
- সরবরাহকারী হলে গত ছয় কর মেয়াদের বকেয়া সনদের তালিকা করে গ্রাহকদের কাছে চেয়ে নিন।
- অ্যাকাউন্টিং সফটওয়্যারে VDS প্রাপ্য ও VDS প্রদেয় আলাদা লেজারে রাখুন।
- চুক্তি ও ক্রয়াদেশে VDS ও মূসক ৬.৬ দেওয়ার শর্ত যোগ করুন।
১১. সাধারণ প্রশ্নোত্তর
মূসক ৬.৬ কোন ধারায় আছে?
নিবন্ধিত VDS সত্তা কত দিনের মধ্যে মূসক ৬.৬ দেবে?
সরবরাহকারী কত দিনের মধ্যে হ্রাসকারী সমন্বয় নিতে পারবেন?
ক্রেতা সনদ না দিলে কী করব?
ভ্যাট কাটা না হলে দায় কার?
Mushak 6.6 is the VAT deduction at source (VDS) certificate. When a bank, company, NGO or government office withholds VAT from a supplier's bill, it must give the supplier this certificate as proof. Without it, the supplier cannot claim a decreasing adjustment in its return and may end up paying the same VAT twice. This guide explains who issues Mushak 6.6, the deadline, what it must contain and how suppliers use it.
1. What is Mushak 6.6 (VDS certificate)?
Section 49 of the Value Added Tax and Supplementary Duty Act 2012 requires certain entities to deduct the specified VAT from the consideration payable to a supplier and deposit it with the government. This is VAT deducted at source, or VDS. Section 53 then requires the withholding entity, when it takes a supply from a registered person, to issue a certificate of deduction at source at the time of payment, in the manner set by the National Board of Revenue. The prescribed form for that certificate is Mushak-6.6.
The logic is simple. The supplier reports the full output VAT on its sale. Part of that VAT has already been paid to the government by the buyer through deduction. Mushak 6.6 is the documentary proof of the deducted amount, and it allows the supplier to take a decreasing adjustment so the same tax is not paid twice.
2. Who must deduct VAT at source
Under the Act and the VDS rules, withholding entities generally include:
- Ministries, divisions and departments; semi-government and autonomous bodies; state-owned enterprises and local authorities.
- Banks, insurance companies and other financial institutions.
- Limited companies.
- Organisations approved by the NGO Affairs Bureau or the Department of Social Services.
- Secondary and higher-secondary educational institutions.
So if your business is a private limited company, you may have to deduct VAT when paying rent, contractors, consultants, security, transport and many other services, and issue Mushak 6.6 each time. Rates depend on the service code; see our TDS and VDS rate chart 2026-27. Under section 49(2), a VDS entity should not take a supply from, or pay, a supplier who is not registered or enlisted and does not issue a tax invoice; if it does, the buyer becomes liable for the applicable VAT.
3. When to deduct and how to deposit
VAT is deducted when the bill is paid. SRO No. 182-AIN/2025/310-MUSHAK dated 27 May 2025, effective 1 July 2025, replaced the 2021 VDS rules. According to an analysis presented at ICAB, the main changes in deposit and certificate timing are:
| Item | Registered VDS entity | Unregistered VDS entity |
|---|---|---|
| How to deposit | Show as an increasing adjustment in the VAT return and pay with net liability | Separate deposit by A-challan or e-payment |
| When | Before filing the return for that tax period | Within 15 days of paying the bill |
| Issue Mushak 6.6 | Within 3 working days after filing the return | Within 3 working days after deposit |
| Proof shown | Return details | Challan or e-payment number and date |
Under the VAT and SD (Amendment) Ordinance 2026, monthly returns are due within 15 days after the tax period ends (20 days for banks, insurers and government or autonomous bodies). VDS on a bill paid in November 2026 therefore goes into the November return, and Mushak 6.6 should reach the supplier within three working days after that return is filed. Read more: monthly VAT return 15-day rule.
4. What the certificate contains
| Part | Details |
|---|---|
| Deductor | Name, address and BIN of the withholding entity (if registered) |
| Certificate | Serial number and date of issue |
| Supplier | Name, address and BIN |
| Invoice | Mushak 6.3 invoice number and date |
| Values | Supply value and VAT shown on the invoice |
| Deducted VAT | The amount actually deducted at source |
| Deposit proof | Return details (registered) or challan / e-payment number and date (unregistered) |
| Signature | Name, designation and signature of the authorised officer |
5. Worked example: calculating VDS
A limited company (a registered VDS entity) pays a registered supplier for a service in November 2026. The consideration payable, including VAT, is Tk 1,07,500, and we assume the VDS rate for that service is 7.5%. (Illustrative figures only; take the actual rate from the rules for the service code.)
| Step | Calculation | Result |
|---|---|---|
| Consideration payable | Bill including VAT | Tk 1,07,500 |
| Tax fraction | 7.5 ÷ 107.5 | — |
| VAT to deduct | 1,07,500 × 7.5 ÷ 107.5 | Tk 7,500 |
| Paid to supplier | 1,07,500 − 7,500 | Tk 1,00,000 |
| Buyer's return | Increasing adjustment, November return | Tk 7,500 |
| Mushak 6.6 | 3 working days after filing | Mid-December |
The supplier reports the full sale and Tk 7,500 output VAT in its November return. Once it receives Mushak 6.6, it claims Tk 7,500 as a decreasing adjustment. The government collects the Tk 7,500 once, through the buyer. If the supplier is unregistered and quotes a price without VAT, the buyer first adds VAT to find the consideration and then applies the tax fraction, and the buyer carries the liability.
6. How suppliers claim the decreasing adjustment
- Issue Mushak 6.3: give a proper tax invoice for every supply, with VAT shown clearly.
- Report full output VAT: show the full value and VAT in the supply section of the return, not the net amount.
- Collect Mushak 6.6: obtain the certificate and match the invoice number, date and amounts.
- Claim the adjustment: take a decreasing adjustment equal to the VAT shown as deducted.
- Watch the time limit: under the 2025 rules the adjustment must be taken in the relevant tax period or within the next six tax periods (previously three).
The most common real-world problem is buyers issuing certificates late. Keep a monthly follow-up list for major customers, and write into contracts and purchase orders that Mushak 6.6 must be issued within the legal time limit whenever VAT is deducted.
7. When VDS does not apply
- Exempt supplies: goods or services in the First Schedule; section 49(1) applies only to supplies that are not exempt.
- Zero-rated supplies: such as exports and deemed exports.
- PKI or POS invoices: under the 2025 changes, no deduction where the invoice is issued from a PKI or POS machine showing the buyer's name and BIN (per the ICAB analysis).
- Locally manufactured medicine: no deduction on purchases of locally made medicine from traders (same source).
The section 49(5) relief for projects, where VAT has already been deducted from the main service provider, is now limited to first-tier sub-contractors and agents according to the same analysis. Lower-tier sub-contractors may face VDS.
Seven common Mushak 6.6 mistakes
- Deducting VAT and issuing Mushak 6.6 without a Mushak 6.3 invoice.
- Applying the rate to the VAT-inclusive amount instead of using the tax fraction.
- Using old rates; for example, construction contractors moved from 7.5% to 10% in 2025.
- Issuing the certificate later than three working days after filing the return.
- Typing the supplier's BIN wrongly.
- Suppliers reporting output VAT net of VDS and then also claiming the adjustment.
- Not keeping certificates and invoices for five years.
8. What businesses should do now
- Confirm whether your entity is a VDS entity; if so, map every supplier to a service code and rate.
- After filing the October 2026 return (due 15 November), issue all pending Mushak 6.6 certificates within three working days.
- If you are a supplier, list missing certificates for the last six tax periods and request them in writing.
- Keep separate ledgers for VDS receivable and VDS payable in your accounting software.
- Add VDS and Mushak 6.6 terms to contracts, or let our monthly compliance retainer handle it.
9. FAQs
Which section requires Mushak 6.6?
When must a registered VDS entity issue Mushak 6.6?
How long does a supplier have to claim the decreasing adjustment?
What if the buyer does not issue the certificate?
Who is liable if VAT is not deducted?
Need help with Mushak 6.6 and VDS? মূসক ৬.৬ ও উৎসে মূসক নিয়ে সহায়তা দরকার?
VATax Advisory & Co. maps your VDS rates, prepares Mushak 6.6 certificates, reconciles decreasing adjustments and files your monthly VAT return on time. আমরা VDS হার নির্ধারণ, মূসক ৬.৬ প্রস্তুত, হ্রাসকারী সমন্বয় মেলানো এবং সময়মতো রিটার্ন দাখিল করে দিই।
Related VAT guides / আরও পড়ুন
- Mushak 6.3 tax invoice guide
- Mushak 6.10: invoices over Tk 2 lakh
- TDS & VDS rate chart 2026-27
- Monthly VAT return: 15-day rule
- Input VAT credit guide
- VAT registration in Bangladesh
Sources: National Board of Revenue (NBR); Value Added Tax and Supplementary Duty Act 2012, sections 49, 53 and 107 (Laws of Bangladesh, bdlaws.minlaw.gov.bd); VAT Deduction and Collection at Source rules, SRO 182-AIN/2025/310-MUSHAK (27 May 2025), as summarised in an ICAB-hosted analysis of 2025-26 VDS changes; VAT and SD (Amendment) Ordinance 2026 on monthly returns. Disclaimer: general information, not legal advice. The worked example uses illustrative figures. VDS rates and procedures change through SROs and general orders; check the current position or consult a professional before acting.

