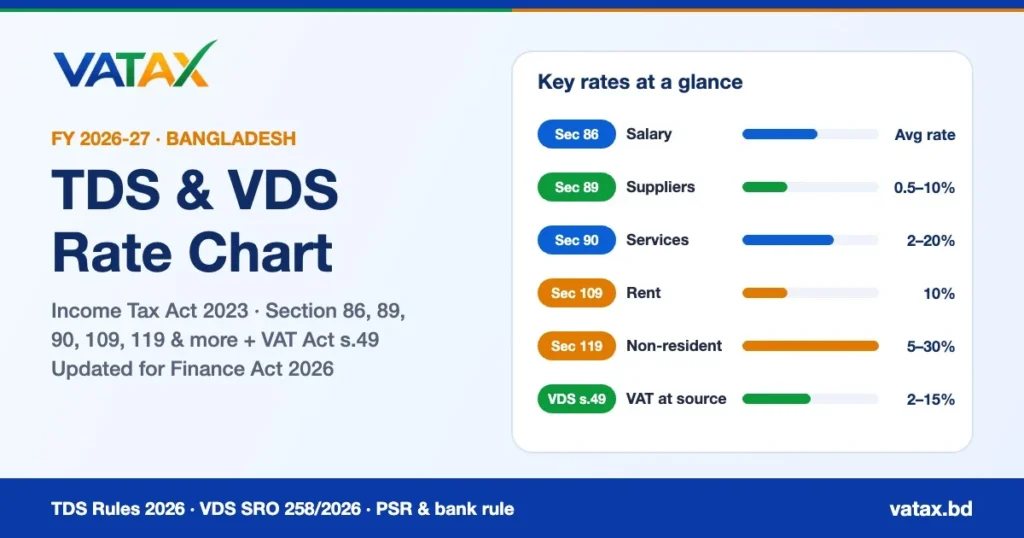
This is your one-page TDS & VDS rate chart for FY 2026-27 in Bangladesh. It covers the key withholding sections of the Income Tax Act 2023 (Section 86 salary, Section 89 contractors & suppliers, Section 90 services, Section 109 rent, Section 119 non-residents and more) and VAT Deduction at Source under Section 49 of the VAT & SD Act 2012, updated for the Finance Act 2026, the Tax Deducted at Source Rules 2026 and the June 2026 VDS amendment. (উৎসে কর ও উৎসে মূসক কর্তনের হার ২০২৬-২৭)
What changed in FY 2026-27 (Finance Act 2026)
Part A – TDS rate chart FY 2026-27 (Income Tax Act 2023)
Under the Income Tax Act 2023, a “specified person” (companies, firms, AOPs, NGOs, government and autonomous bodies, and individuals with large business turnover) must deduct tax at source when making these payments. They must deposit the tax and file the withholding tax return. Below is a short description and a quick chart for each key section.
Salary (বেতন)
Every employer must deduct tax from salary each month at the average rate. Work out the employee’s estimated tax for the year (after the investment rebate), then spread it over the months of employment.
Contractors, suppliers & manufacturers (ঠিকাদার ও সরবরাহকারী)
Tax is deducted from payments for supply of goods, contracts, manufacturing, processing, construction and engineering work. The rate depends on the item (TDS Rules 2026). The default rate is 5%.
Payment for services (সেবা প্রদানের বিপরীতে)
This covers fees paid to residents for professional, technical, agency and other services. For some services the rate depends on whether the payee is a natural person or a firm or company.
Rent (ভাড়া)
A specified person paying rent must deduct tax at a flat 10%. This covers rent for a house, office, shop, warehouse or godown, vacant land or premises, hotel or guest house, plant and machinery, and private water bodies.
Other common TDS rates at a glance
These sections each have one or two fixed rates. Here they are in one chart.
Payments to non-residents (অনিবাসী)
Tax must be deducted before paying any non-resident, including foreign consultants, parent companies and overseas suppliers. If a tax treaty (DTAA) gives a lower rate, you can apply it with a valid tax residency certificate and NBR’s reduced-rate certificate where required.
The 50% higher rate: PSR and banking channel
When the payee cannot show Proof of Submission of Return (PSR) where it is required, the payer must deduct at a rate 50% higher than the normal rate. The TDS Rules 2026 apply the same increase when a payment is made outside the banking channel. For example, a 5% supply rate becomes 7.5%.
| Case (goods supply, normal rate 5%) | Bank transfer | PSR shown | TDS rate |
|---|---|---|---|
| Fully compliant | Yes | Yes | 5% |
| Cash payment | No | Yes | 7.5% |
| No PSR | Yes | No | 7.5% |
| Cash + no PSR | No | No | 10% |
Part B – VDS rate chart FY 2026-27 (VAT & SD Act 2012)
VAT Deduction at Source (উৎসে মূসক কর্তন)
A withholding entity must deduct VAT from the supplier’s bill, deposit it to the treasury, and give the supplier a Mushak 6.6 certificate. Withholding entities include government, semi-government and autonomous bodies, NGOs, banks, insurers and financial institutions, educational institutions, and limited companies. The supplier then claims a decreasing adjustment (Section 50). The list of services comes from the VDS Rules 2025, as amended by SRO 258-Law/2026/358-VAT (7 June 2026).
Worked example: TDS + VDS on one bill
A private limited company pays a consultancy firm a bill of Tk 1,00,000 + 15% VAT (Tk 15,000), by bank transfer. The firm has shown its PSR.
| Item | Rule | Amount (Tk) |
|---|---|---|
| Service value | Bill before VAT | 1,00,000 |
| VAT on bill | 15% | 15,000 |
| TDS deducted | Section 90 – firm/company, 7.5% | 7,500 |
| VDS deducted | Section 49 – S032.00, 15% | 15,000 |
| Net paid to the consultancy firm | 1,15,000 − 7,500 − 15,000 | 92,500 |
Frequently asked questions
What is the TDS rate under Section 89 for FY 2026-27?
Section 89 has item-wise rates under the TDS Rules 2026. They range from 0.5% (listed farm goods, gold, silver) to 10% (tobacco raw materials). Manufacturing, construction and engineering works, and all unlisted goods, are at 5%.
What is the TDS rate on rent under Section 109?
10% of the rent paid, deducted by a specified person. This applies to house, office, shop, warehouse, premises, plant and machinery rent. The tenant also deducts 15% VAT on space rent under the VDS rules.
What is the difference between TDS and VDS?
TDS is income tax deducted from a payment under the Income Tax Act 2023. It becomes a tax credit for the payee. VDS is VAT deducted from a supplier’s bill under Section 49 of the VAT & SD Act 2012. The supplier adjusts it in the VAT return using Mushak 6.6.
What happens if the payee has no PSR?
Where PSR is required and not shown, TDS is deducted at a rate 50% higher than normal. For example, 5% becomes 7.5%.
Which TDS rates changed in FY 2026-27?
Lottery and online game winnings went up to 25%. Export cash subsidy came down to 5%, and electricity purchase to 3%. There is a new 0.5% rate on purchase of gold, silver and precious stones, and a new 0.2% advance tax on sales to retailers.
VATax Advisory & Co. sets up withholding systems, files quarterly TDS returns and VAT returns, and reviews payments to non-residents for companies and foreign investors.
Quarterly TDS returnCompliance retainerTalk to us
Related: TDS calculator · VDS calculator · TDS & VDS rates 2025 (previous year) · Tax & VAT MCQ test
Sources: Income Tax Act 2023 (Sections 86–125, 140, 142); Finance Act 2026; Tax Deducted at Source Rules 2026 (as amended incl. SRO No. 273-Law/Income Tax-5/2026), NBR income tax rules; VAT & SD Act 2012 (Sections 49–50); VDS Rules 2025 (SRO No. 182-Law/2025/310-VAT) as amended by SRO No. 258-Law/2026/358-VAT; PwC Bangladesh – Finance Act 2026 key amendments; PwC Worldwide Tax Summaries – Bangladesh WHT.
Disclaimer: This chart is a summary for general information, current as of 19 October 2026. NBR can amend rates by SRO at any time, and many items have conditions and exceptions. Check the official rules or ask a professional before making a payment.

